
E3G urges IMF, World Bank & G20 to tackle climate debt
Mon, 19th Oct 2026 (Today)
E3G has urged the IMF, World Bank and G20 to address the structural causes of economic vulnerability in poorer countries. The think tank made the call following the IMF's latest World Economic Outlook and as the IMF-World Bank Annual Meetings in Bangkok drew to a close.
Its intervention focused on pressures facing low-income and energy-importing economies. The IMF warned that economic resilience was becoming more uneven, while E3G highlighted the combined effects of energy, debt and climate shocks.
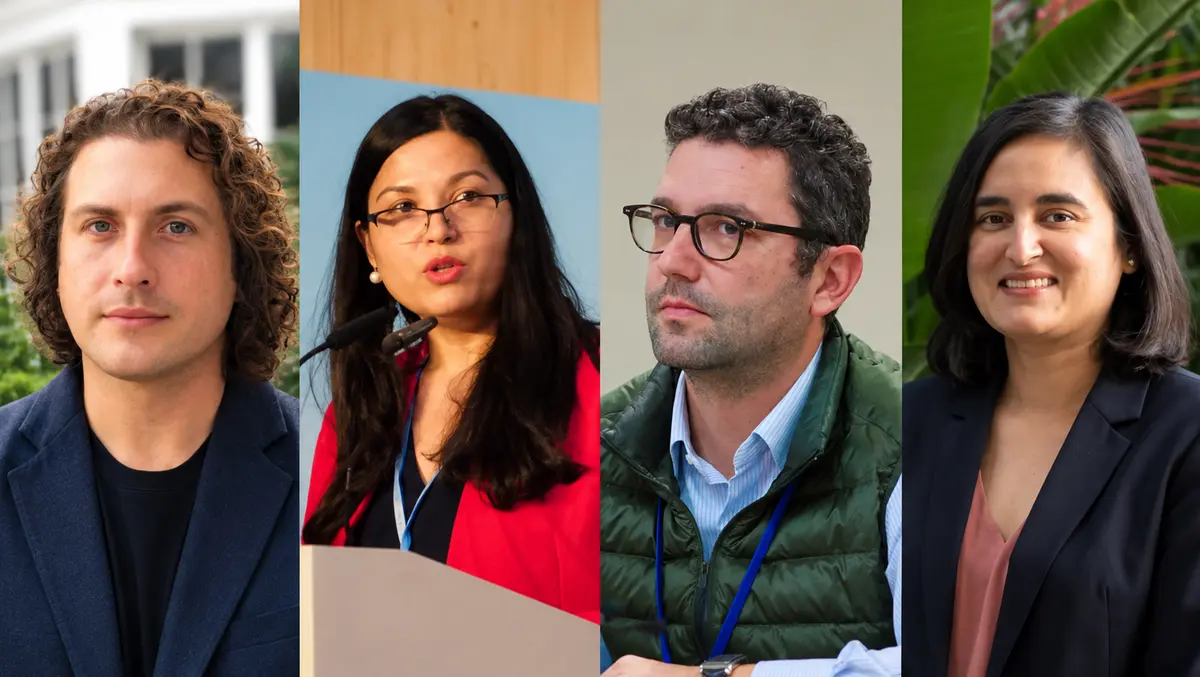
"The IMF's October 2026 World Economic Outlook is a reminder that poorer member states face a compounding crisis: the spillovers of the Iran war, rising interest rates in developed countries, and an El Niño-intensified climate emergency worsening food insecurity. The IMF, the World Bank and the G20 must meet this moment, providing immediate emergency liquidity where necessary while helping mobilise longer-term finance for more resilient growth paths," said Salvatore Serravalle, Programme Lead, Global Macro and Finance Resilience at E3G.
The comments reflect a wider debate over how multilateral lenders should respond as climate risks become more central to macroeconomic policy. Debt distress, higher borrowing costs and energy import bills have narrowed fiscal space in many developing economies. This has raised questions about whether international institutions are addressing underlying vulnerabilities or focusing mainly on short-term crisis management.
Jurei Yada, Associate Director, Finance and Resilience at E3G, argued that repeated borrowing could not replace changes to vulnerable states' economic models. She linked resilience to energy dependence and the terms on which countries access finance.
"Effective action requires an honest assessment of what is driving these crises. Discussions on economic resilience cannot overlook the structural vulnerabilities created by dependence on volatile international fossil fuel markets. Governments cannot sustainably borrow their way through successive shocks while leaving the underlying sources of exposure unaddressed. Multilateral discussions must connect immediate crisis response with longer-term economic resilience. This means ensuring vulnerable economies have access to the liquidity needed to protect people and sustain investment through shocks, alongside financing for clean energy, resilient infrastructure and disaster preparedness that reduces the costs of future crises," Yada said.
As the meetings ended, E3G reiterated its concerns that discussions had not fully addressed the root causes of instability in developing countries, despite debt, food inflation and climate-related disruption remaining high on the agenda.
"Amid high energy prices, food inflation, El Niño impacts and rising debt – with developing countries hit hardest – these Annual Meetings steered largely clear of addressing the root causes of these crises. There is no resilient future without addressing climate change as an economic imperative and ensuring more and better finance flows to enable economies to transition to sustainability," Yada said.
E3G also linked the discussions to a broader political agenda, arguing that debt, development and climate policy should be treated as connected issues rather than separate areas of international finance.
"Ed Miliband is right to put debt, development and climate on the same agenda. The energy crisis, climate vulnerability and debt distress are converging. The G20 has shown in the past that it can manage global crises effectively. Turning that proven capacity to the climate-debt-development challenge is now the UK's test," Serravalle said.
Alongside its criticism, E3G highlighted proposals discussed in Bangkok, including targeted liquidity support, more effective debt restructuring, guarantees to lower financing costs and greater use of concessional funding where commercial finance remains too expensive or scarce.
Debate also focused on multilateral development banks. The World Bank and other lenders face pressure to demonstrate that more funding is reaching higher-risk markets while maintaining climate commitments and expanding lending.
"Balance sheet stretching, guarantee issuing, private capital mobilising – the IMF-World Bank meetings in Bangkok were full of promising signals, and buzzwords, for the year ahead. The test will be for these institutions, and their fellow multilateral development banks, to expand finance flows without sacrificing their climate credentials," said Danny Scull, Senior Policy Adviser, Public Banks and Development at E3G.
Seleha Lockwood, Programme Lead, Public Banks and Development at E3G, stressed that public banks must maximise the impact of limited climate finance while ensuring funding reaches vulnerable communities. She said the test for the Bangkok discussions was whether public banks could mobilise more private investment in clean energy and resilient infrastructure while measuring success by the results achieved and the amount of funding delivered.
"Every public dollar needs to do more and do it more equitably. Bangkok's test is whether public banks can unlock significantly more private investment for clean energy and resilient infrastructure, while directing limited concessional finance to climate resilience for vulnerable communities. We need to judge success by what the money achieved and whether enough money actually moved," Lockwood said.